In this article
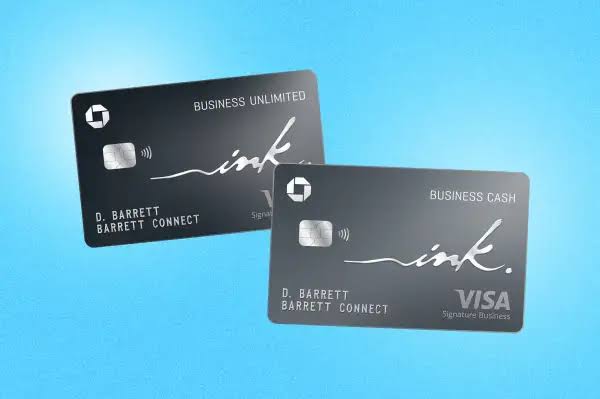
Small business owners often want a credit card that rewards their everyday operating costs without charging them a fee just to hold it. The Chase Ink Business Cash Credit Card aims squarely at that audience, combining generous bonus categories on common business expenses with a $0 annual fee. This review walks through how the card works, what it earns, and whether it makes sense for your business.
Overview of the Ink Business Cash
The Ink Business Cash is a no-annual-fee business card from Chase built around tiered cash-back categories that align with how many small companies actually spend. Rather than offering a flat rate on everything, it concentrates its richest rewards on office supplies and telecom services — two areas where business spending tends to be steady and predictable. It is part of the broader Chase Ink family, which also includes the Ink Business Unlimited and the premium Ink Business Preferred.
Despite the “cash back” name, rewards are technically earned as Chase Ultimate Rewards points, a detail that becomes valuable if you also hold a premium Chase card. For a business that doesn’t need a complex travel-rewards setup, that flexibility is a quiet bonus rather than a requirement, which is part of what makes the card approachable for first-time business cardholders.
Annual Fee and Cost Structure
The card has a $0 annual fee, which is a major draw for cost-conscious owners and freelancers. There’s no pressure to hit a spending minimum just to break even on the card itself.
As with most rewards cards, the trade-off is the interest rate. The Ink Business Cash typically offers an introductory 0% APR on purchases for a promotional window after account opening, after which a variable APR applies based on creditworthiness. That intro period can be useful for financing early equipment or inventory purchases, but carrying a balance long term will quickly outweigh any cash back you earn. Foreign transaction fees generally apply, so it is not ideal for businesses with significant overseas spending.
Rewards and Earning Categories
The earning structure is where this card shines for the right business:
- 5% cash back on the first $25,000 spent each account year in combined purchases at office supply stores and on internet, cable, and phone services.
- 2% cash back on the first $25,000 spent each account year at gas stations and restaurants combined.
- 1% cash back on all other purchases, with no cap.
That $25,000 annual cap on the 5% and 2% tiers is the key limitation to understand — once you cross it, those categories drop to 1%. New cardholders also frequently see a sizable welcome bonus after meeting a spending requirement in the first few months, and the card has at times featured limited-time bonus categories such as elevated rewards on rideshare services.
Benefits Beyond Cash Back
Because rewards are Ultimate Rewards points, you can redeem them for cash back, gift cards, travel through Chase, or statement credits. The hidden advantage appears when you also hold a card like the Ink Business Preferred or a Sapphire card: you can combine points and unlock transfers to airline and hotel partners, which can substantially increase their value beyond a straight 1-cent-per-point cash redemption.
The card also includes typical business-card tools such as free employee cards, spending controls, and integrations that make expense tracking easier at tax time. Standard Visa business protections, like purchase and travel-related coverages, round out the package, though specific benefits can change. Many owners also value that employee cards earn rewards at the same rates, so spending by your team contributes to the same pool of points without extra cost. The ability to set individual spending limits on those employee cards adds a layer of control that growing businesses tend to appreciate as headcount increases.
Pros and Cons
- Pro: Strong 5% rate on office supplies and telecom — categories many businesses use heavily.
- Pro: No annual fee, keeping it affordable for any size business.
- Pro: Points become far more valuable when paired with a premium Chase card.
- Pro: Free employee cards and useful expense-management features.
- Con: The $25,000 annual cap limits the top-tier earning for high spenders.
- Con: No flat high rate on general spending, so non-category purchases earn just 1%.
- Con: Foreign transaction fees make it weak for international expenses.
- Con: Requires a genuine business (even a sole proprietorship) to qualify.
Who It Suits and Who Should Look Elsewhere
The Ink Business Cash is ideal for small businesses, side hustlers, and freelancers whose spending leans toward office supplies, software, and phone or internet services. If your monthly expenses naturally fall into the 5% categories, the rewards add up quickly with no annual cost. It is especially powerful for owners who already participate in the Chase ecosystem and want to pool points for travel.
Businesses with large, evenly spread spending across many categories may prefer a flat-rate business card that pays the same percentage on everything without caps. Likewise, companies with heavy international purchasing should look for a card without foreign transaction fees.
Tips for Getting the Most Value
Funnel your office-supply and telecom spending — including software and subscriptions purchased through office-supply retailers — onto this card to maximize the 5% tier before hitting the cap. Pair it with a flat-rate card to cover everything outside the bonus categories. If you can, hold a premium Chase card so your points gain transfer-partner potential. And always pay the balance in full once any intro APR period ends, since interest charges will erode your rewards faster than the cash back accumulates.
Final Verdict
The Chase Ink Business Cash is one of the strongest no-annual-fee business cards available for owners whose spending fits its bonus categories. The 5% on office supplies and telecom, combined with zero annual cost and the option to upgrade points into travel value, makes it a smart cornerstone card for many small businesses. Just keep the $25,000 caps and the modest base rate in mind, and pair it with the right complementary card to cover the gaps.
This article is for general informational purposes only and does not constitute financial advice. Rates, fees, and terms are subject to change — verify the latest details with the card issuer before applying.