In this article
If you are working to rebuild your credit or establish a credit history for the first time, the DESTINY™ Mastercard® is one of the cards you will almost certainly come across. Marketed directly to consumers with fair or bad credit, it promises a real, unsecured line of credit with no security deposit required. But convenience comes at a cost. In this complete guide, we break down exactly how the card works, what it costs, who it is built for, and whether it deserves a place in your wallet.
What Is the DESTINY Mastercard?
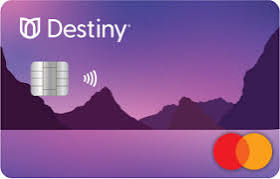
The DESTINY Mastercard is an unsecured credit card issued by Genesis FS Card Services and designed for people with limited or damaged credit. Unlike a secured card, it does not require you to put down a refundable deposit to open the account. Instead, you receive a modest starting credit line — typically at least $700 — based on the offer you are pre-qualified for. Because it carries the Mastercard network logo, it is accepted virtually anywhere Mastercard is taken, both in stores and online.
The card’s core selling point is accessibility. Applicants who have been turned down for mainstream rewards cards can often still qualify here, and the issuer offers a pre-qualification check that does not affect your credit score, so you can see your odds before formally applying.
Fees and Costs You Need to Know
This is where the DESTINY Mastercard demands careful attention. The card is built around fees, and they add up quickly:
- Annual fee: $175 for the first year, then $49 each year afterward.
- Monthly fee: waived for the first year, then $12.50 per month — an additional $150 annually — starting in year two.
- APR: a high 35.9% variable rate on purchases.
It is important to understand how those fees interact with your credit limit. Because the first annual fee is charged when you open the account, a $700 limit does not mean $700 of immediate spending power — the fee is deducted up front. By the second year, between the annual fee and the monthly fees, you could be paying roughly $199 per year simply to keep the card open, before you have charged a single dollar of interest.
How the Card Helps You Build Credit
The most valuable feature of the DESTINY Mastercard is something it does quietly in the background: it reports your account activity to all three major credit bureaus — Experian, Equifax, and TransUnion — every month. This is the mechanism that allows a credit-builder card to actually do its job.
When you use the card responsibly, that positive history is recorded on your credit reports. The two factors that matter most are payment history (paying on time, every time) and credit utilization (keeping your balance low relative to your limit). If you charge a small amount each month and pay the statement in full, you can steadily demonstrate creditworthiness and improve your score over time — potentially qualifying for better, lower-cost cards within a year or two.
Mastercard Benefits and Protections
As a Mastercard product, the DESTINY card includes the standard network-level protections you would expect, even at the entry level:
- Zero liability protection for unauthorized purchases, so you are not held responsible for fraudulent charges.
- Identity theft protection resources provided through the Mastercard network.
- Worldwide acceptance anywhere Mastercard is recognized.
These are useful safety nets, though they are not unique to this card — nearly every Mastercard offers them.
The Pros and Cons
Pros:
- No security deposit required, unlike secured cards.
- Pre-qualification available with no impact on your credit score.
- Reports to all three credit bureaus.
- Accessible to applicants with fair or poor credit.
Cons:
- Steep annual fee and recurring monthly fees from year two onward.
- Very high 35.9% APR — carrying a balance is expensive.
- Low starting credit limit.
- No rewards, cash back, or sign-up bonus.
Who Should Consider It — and Who Should Not
The DESTINY Mastercard can make sense for a narrow group of people: those who cannot qualify for anything better and who specifically do not have the cash for a secured card’s deposit. If that describes you, and you commit to paying the balance in full every month to avoid the punishing APR, the card can serve as a stepping stone toward stronger credit.
For most others, though, the math is hard to justify. If you can come up with a refundable deposit, a secured credit card typically offers the same credit-building power with far lower fees — and you get your deposit back when you close or upgrade the account. The fees attached to the DESTINY card mean you are effectively paying a premium for the convenience of skipping a deposit.
How to Use It Wisely
If you decide the DESTINY Mastercard is right for you, treat it as a tool, not a spending account:
- Charge only small, planned purchases you can pay off immediately.
- Pay the statement balance in full every month to avoid the 35.9% APR entirely.
- Keep your utilization below 30% — ideally under 10% — of your limit.
- Set up autopay so you never miss a due date.
- Reassess after 12 months and apply for a no-fee or rewards card once your score has improved.
Final Verdict
The DESTINY Mastercard delivers on its promise of accessible, deposit-free credit for people rebuilding their financial lives, and its monthly reporting to all three bureaus genuinely can help raise your score. But those benefits come wrapped in some of the highest fees in the credit-builder category. Used carefully and temporarily — as a bridge to better products — it can be worthwhile. Used as a long-term card or one you carry a balance on, it becomes an expensive habit. Before applying, weigh it honestly against a secured card, and always confirm the current fees, APR, and terms directly with the issuer, as these can change.
This article is for general informational purposes only and does not constitute financial advice. Rates, fees, and terms are subject to change — verify the latest details with the card issuer before applying.