In this article
Building credit from scratch usually means choosing between a secured card that locks up a deposit or a high-fee unsecured card that costs you for the privilege. The Current Build Card takes a different path, tying a credit-building card directly to a mobile banking account. This review breaks down how it works, what it costs, and whether its unusual structure makes it worth a spot in your wallet.
A Closer Look at the Current Build Card
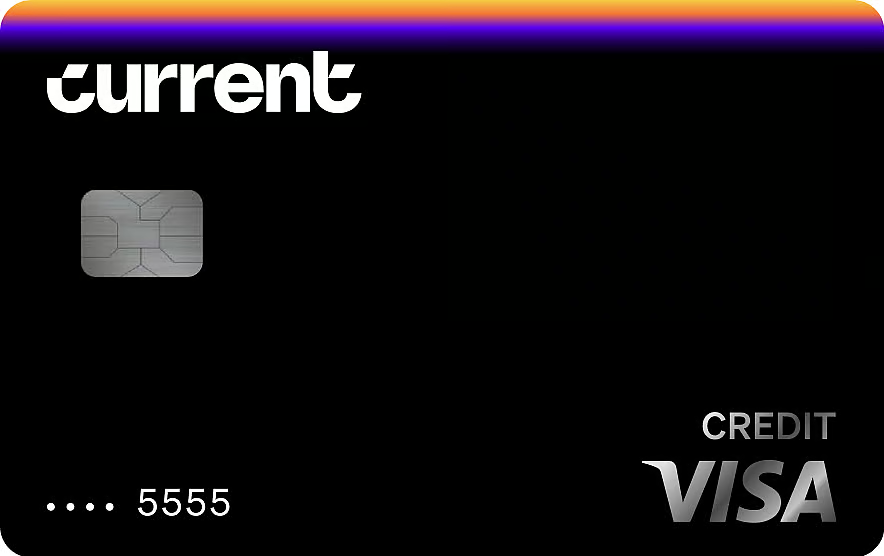
The Current Build Card is a Visa card linked to the Current banking app, issued in partnership with Cross River Bank. It is designed for people who are new to credit or rebuilding it. Rather than functioning like a traditional revolving credit card, it works more like a secured charge card that draws from money you already hold in your Current account.
The key selling point is that there is generally no credit check and no separate security deposit to open it. Your own balance effectively backs your spending, which removes the typical barriers to approval for credit newcomers.
This hybrid model blurs the line between a debit card and a credit-building card. You experience the day-to-day convenience of spending money you already have, while the activity is reported as credit behavior. For someone nervous about debt, that structure can feel safer than a traditional revolving card that lets balances grow.
How It Works and What It Costs
When you make a purchase with the Build Card, the funds are drawn against your available Current account balance, so you are spending money you already have. That activity is then reported to the three major credit bureaus as credit behavior, which is how it helps build your score without the risk of running up traditional debt.
As of recent information, the card carries no annual fee. That said, other charges can apply depending on how you use it, such as out-of-network ATM fees, foreign transaction fees, and late fees. Because terms can change, confirm the current fee schedule in the Current app before relying on the card.
Rewards and Account Features
The Build Card offers a modest points-based rewards program. You can earn points on eligible purchases, with a higher earning rate unlocked when you set up a qualifying payroll direct deposit into your Current account. The boosted rewards are tied to that direct deposit, so the program rewards people who make Current their primary banking hub.
Because the card lives inside a banking app, you also get the features of the broader Current account, including real-time transaction notifications, mobile money management, and the convenience of seeing your spending and credit-building activity in one place.
Advantages and Drawbacks
- Advantage: No credit check and no separate deposit to open.
- Advantage: No annual fee under current terms.
- Advantage: Reports to all three major credit bureaus.
- Advantage: Spends from your own balance, reducing debt risk.
- Drawback: Best rewards require qualifying direct deposit.
- Drawback: Other fees like ATM and foreign transaction can apply.
- Drawback: Limited rewards compared with mainstream cards.
- Drawback: No clear upgrade path to a traditional card.
Who Benefits and Who Should Look Elsewhere
The Current Build Card is a sensible choice for someone who is new to credit or rebuilding, wants to avoid a hard credit check, and is comfortable managing money through a mobile app. It is especially convenient if you are willing to route your paycheck into Current via direct deposit, since that unlocks the better rewards rate.
People who want to earn substantial rewards, who prefer a traditional bank with branches, or who eventually want to graduate to a higher-limit card from the same issuer may find it limiting. Those looking for a card that clearly transitions into premium products down the road might prefer a secured card from a large bank with a defined upgrade path.
Tips for Using It Effectively
To get the most value, set up the qualifying direct deposit so you capture the higher rewards rate rather than the base earning. Keep enough money in your Current account to comfortably cover your purchases, and review the fee schedule so you avoid out-of-network ATM and foreign transaction charges. Use the card consistently for small, regular purchases to keep the credit-building reports flowing, and pay attention to the app’s notifications to stay on top of your activity. Since there is no built-in upgrade path, plan ahead to apply for a traditional card once your score has improved.
Final Assessment
The Current Build Card is a thoughtful, low-barrier tool for establishing credit without a deposit or a hard inquiry. Its no-annual-fee structure and bureau reporting make it a legitimate starter option, particularly for people who already bank with Current. The trade-offs are modest rewards, assorted situational fees, and the lack of a defined upgrade path. For credit newcomers who value simplicity and app-based money management, it is a reasonable first step, provided you eventually move on to a fuller-featured card.
This article is for general informational purposes only and does not constitute financial advice. Rates, fees, and terms are subject to change — verify the latest details with the card issuer before applying.